The Local Pool Is Smaller Than You Think
What 12 months of Wisconsin data says about where purchase business really comes from, and what changes when your market isn't limited to your zip code.
Most loan officers think their growth problem is visibility. More posts. More coffee meetings. More open houses. If the right agents just knew who they were, the referrals would follow.
I pulled the numbers, and I don't think visibility is the problem. I think it's math.
What the Data Shows
Using RETR data for Wisconsin, statewide, over 12 months from today, here's what I found:
- There are 14,495 registered real estate agents in Wisconsin.
- 311 of them, about 2.1% or roughly 1 in 47, did 24 or more buy-side transactions.
- 52 of them, about 0.36% or roughly 1 in 279, did 48 or more.
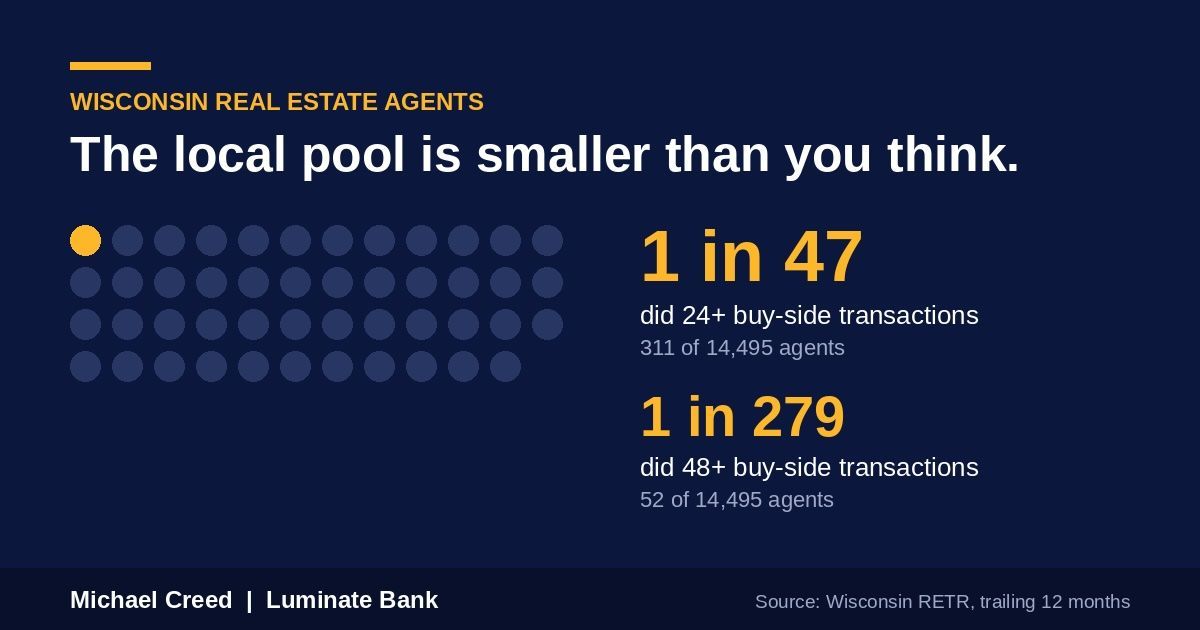
Buy sides are where purchase loans come from. That means a very small group of agents is involved in an outsized share of the purchase business every loan officer in the state is chasing. And that's before cash deals, which take even more of those transactions off the table.
Everyone Has the Same Short List
If your whole plan is local, your best prospects fit on one page. And every other loan officer in your market is working from that same page.
At that point, you're not really competing on value. You're competing on timing, on price, and on who showed up first. That's a hard way to build a business, no matter how good you are.
It's also worth being honest about something. The agents doing 24 or more deals a year are busy, and in my experience most of them already have a lender they trust. Winning one usually means replacing someone. That can happen, but it's slow, and it can be fragile.
What Changes When the Map Gets Bigger
When you work for a lender that is chartered in all 50 states, your referral network isn't capped by your zip code.
Your past clients have family and friends in other states. They relocate. They buy second homes. They help their kids buy their first one. A relationship you built here can follow a client wherever they buy.
And agents stop being the only door. Wealth managers and other professionals who advise people on big financial decisions serve clients everywhere, not just in one county. They care a great deal about who they introduce their clients to. Earn that trust, and the referrals can come from anywhere.
None of this means local stops mattering. Local relationships are still the foundation. It means local stops being the ceiling.
Three Shifts Worth Making
- Ask where your clients' people live. Your past clients' networks are a map you already have.
- Build relationships with advisors, not just agents. The professionals your clients already trust can become your best referral partners.
- Treat out-of-state referrals as part of the plan. Not an exception you figure out when it happens.
Let's Compare Notes
If you're a loan officer wondering what a national business could look like for you, I'm happy to have that conversation. No pitch, just a real look at the numbers. Connect with me on LinkedIn or send me a message here.